
Quick answer: Michael and Susan Dell’s $250 gifts are going into the Trump Accounts of about 25 million children born from 2016 through 2024. Parents don’t apply, but they must claim the child’s account to see and use the money.
Dell $250 deposits are landing in American children’s Trump Accounts this week. Michael and Susan Dell’s $250 gifts are going to about 25 million kids born from 2016 through 2024, and Invest America, the group running the Dell program, says every deposit is expected to be made by the end of the day Friday, Oct. 9. Parents don’t have to apply, but you do have to claim the account to see whether the money arrived.
Here’s who qualifies, how to check your child’s account, and what to do if the $250 isn’t there.
The $250 at a glance
- Amount: $250, one time, from Michael and Susan Dell’s $6.25 billion gift
- Who: children born 2016–2024 in ZIP codes with a median family income of about $118,000 or less, plus children on military bases
- When: deposits expected by end of day Friday, Oct. 9; check the account early next week
- Do you need to apply? No. It’s deposited automatically, even into unclaimed accounts
- Where it goes: invested in an S&P 500 index fund inside the child’s Trump Account, locked until age 18
Who Gets the Dell $250?
The Dells pledged $250 each for 25 million children. Because the Treasury automatically opened a Trump Account for about 70 million kids on Oct. 1, far more children became eligible than the gift could cover. So the money went to the lowest-income ZIP codes first and moved up the income scale until 25 million children were reached.
- Born 2016 through 2024 (children born in 2025 or later get the government’s $1,000 deposit instead)
- Living in a ZIP code with a median family income of about $118,000 or less, based on Census Bureau data
- Children on military bases are included no matter which ZIP code they’re in
When the Dells first announced the gift in December 2025, the cutoff was $150,000. The final limit is lower, so roughly 3,500 ZIP codes that would have qualified no longer do, according to an Investopedia analysis of Census data. That analysis estimates about 7 in 10 children under 10 still live in a qualifying ZIP code. Invest America says families who enrolled before Oct. 1 stay eligible under the rules that applied when they signed up.
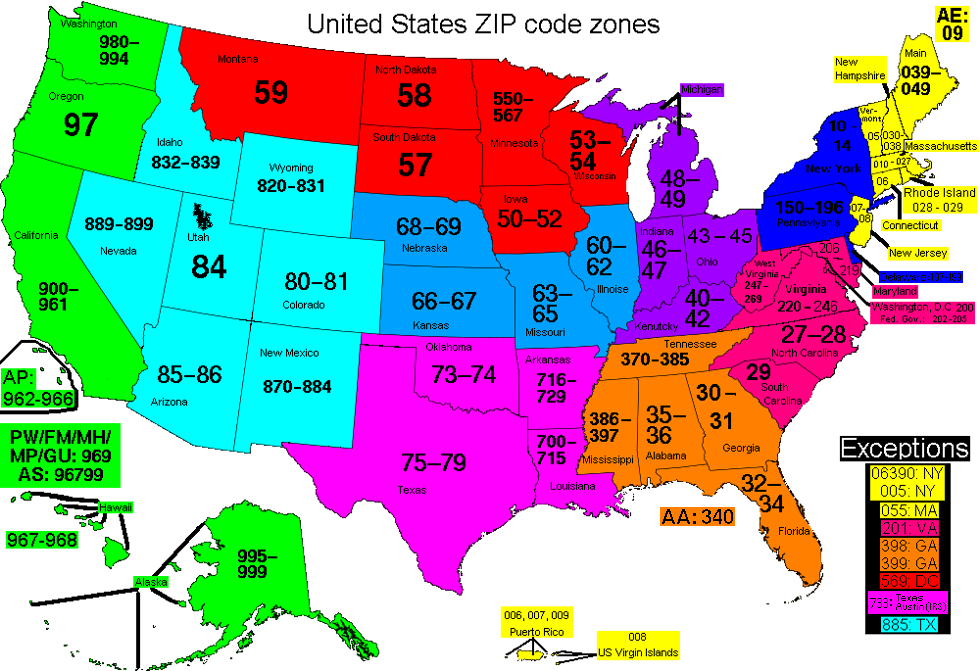
How to check your ZIP code: Invest America points parents to the Census Reporter table of median family income. Type in your ZIP code, select it, and compare the figure with the roughly $118,000 limit.
How to Check If Your Child Got the $250
You can’t see a Trump Account’s balance until a parent or guardian claims it. Here’s how:
- Open the official Trump Accounts app (Apple App Store or Google Play) or go to TrumpAccounts.gov.
- Verify your identity and your relationship to the child.
- Find your child’s account and look at the balance and contribution history for the $250 deposit.
- Didn’t see it yet? Invest America says to check again early next week, since deposits run through Friday.
If you already claimed the account or filed IRS Form 4547 before Oct. 1, you don’t need to do anything else. For separated parents, note that whoever claims the account first controls it.
⚠️ Scam warning: the Dell $250 is free and automatic. Nobody legitimate will call, text or email asking for a fee or your child’s Social Security number to “release” it. Use only the official app or TrumpAccounts.gov.
What Happens to the $250?
The money isn’t paid to parents as cash. Until a parent claims the account and picks something else, it’s invested automatically in a single fund that tracks the S&P 500, the index of 500 large U.S. companies. It can’t be withdrawn until the child turns 18, when the account generally becomes a traditional IRA.
Small amounts can grow over time. Investopedia estimates that a $250 deposit for a 1-year-old could be worth about $1,260 by age 18 if returns match the stock market’s long-run average of roughly 10% a year. That isn’t guaranteed: markets can fall, and fees and inflation reduce real returns.
Didn’t Get the $250? Here’s Why
- Your child was born in 2025 or later. They qualify for the Treasury’s $1,000 deposit instead, but you must claim the account to get it. See our full Trump Accounts guide.
- Your ZIP code’s median family income is above about $118,000, unless you live on a military base or enrolled before Oct. 1.
- Your child was born before 2016. The Dell gift only covers 2016–2024 births.
- The deposit is still on its way. Deposits are scheduled through Friday, Oct. 9.
Why the Dells Are Doing This, and the Criticism
“We’ve seen what happens when a child gets even a small financial head start, their world expands,” Michael Dell said, according to TIME.
Not everyone thinks the program goes far enough. Madeline Brown of the Urban Institute told TIME that lower-income families should get more money rather than the same amounts as everyone else, and that her research found lower-income families are less aware of Trump Accounts in the first place.
Trump Account rules at a glance
The Dell $250 lives inside a Trump Account, so the account’s rules decide what happens next. Here are the key facts from TrumpAccounts.gov and the IRS.
| Rule | What it means for your family | Source |
|---|---|---|
| $1,000 Treasury deposit | For U.S. citizen children born Jan. 1, 2025 through Dec. 31, 2028. A parent must make the election. | TrumpAccounts.gov, IRS |
| $250 Dell deposit | For children born 2016–2024 in qualifying ZIP codes (see above). | Invest America |
| Family contributions | You can add up to $5,000 per year for each child. | TrumpAccounts.gov |
| Employer contributions | An employer may put in up to $2,500 a year tax-free for an employee or dependent. Rules are still in proposed form. | IRS IR-2026-90 |
| Who controls the account | A parent is the custodian until the child turns 18. Then control moves to the child. | TrumpAccounts.gov |
| Using the money | After 18, money can go to qualified expenses like education or a first home. Withdrawals may be taxed as ordinary income. | TrumpAccounts.gov |
| Help line | Trump Account call center: 866-USA-4547. | TrumpAccounts.gov |
Rules for some of these items, like employer contributions, are still being finalized. Check the official FAQ in the Trump Accounts app or call the help line before you plan big deposits.
Should you add your own money?
You don’t have to. The $250 can sit and grow on its own. But a small, steady deposit can make a big difference over 15 years or more.
Here is a made-up example, not a forecast. Say a parent adds $25 a month for a child who is 4 years old today. That is $300 a year, or $4,200 by age 18 before any growth. If the market grows, the balance could be much higher. If the market falls, it could be lower. Nothing is guaranteed.
Before you add money, ask yourself three questions:
- Do I have an emergency fund first? Money in a Trump Account is locked until the child turns 18.
- Is a 529 college plan a better fit? A 529 can be used for school costs before 18.
- Will my employer contribute? Ask HR whether your company plans to add money for employees’ children.
Also read: How to start investing with $100 in index funds. It explains the same S&P 500 funds your child’s account uses.
How to spot a real Treasury message and avoid scams
Big free-money programs attract scammers fast. TrumpAccounts.gov says Treasury and its providers may contact you by email, text or automated call. It also says first activation emails come only from no-reply@TrumpAccounts.Treasury.gov.
| Real | Fake |
|---|---|
| Email from no-reply@TrumpAccounts.Treasury.gov | Email from a Gmail, Yahoo or look-alike address |
| Asks you to open the official app or TrumpAccounts.gov | Sends a link to a strange website |
| Never charges a fee to get the $250 | Asks for a “processing fee” or gift card |
| You call 866-USA-4547 if unsure | Caller pressures you to act today |
If you get a suspicious message, do not click. Report it at ReportFraud.ftc.gov.
Mistakes parents make with the $250
- Not claiming the account. The money may be there, but you can’t see or manage it until you claim it.
- Waiting too long between separated parents. Whoever claims first controls the account. Talk it over early.
- Expecting cash. The $250 is invested, not paid out. It can’t be spent before 18.
- Selling in a panic. Stocks go up and down. A long time horizon is the point of this account.
- Sharing a child’s Social Security number with a caller. Use only the official app or website.
Recommended products
- Kids’ piggy banks that count savings
- Money books for kids
- Investing books for teens
- Fireproof boxes for birth certificates and records
Disclosure: As an Amazon Associate, Nexgen Headlines earns from qualifying purchases.
Sources: Invest America’s Dell eligibility page; Investopedia (via Yahoo Finance); TIME; TrumpAccounts.gov. IRS IR-2026-90 (employer contributions); FTC ReportFraud. This article is for general information and isn’t financial advice.
Last reviewed: Oct. 27, 2026. Facts are as reported when this story was published on Oct. 9, 2026.