
France Debt Crisis
France Debt Crisis Is Colliding With a Growing Student Movement
France Debt Crisis concerns are becoming increasingly difficult to separate from the wave of student protests spreading across the country.
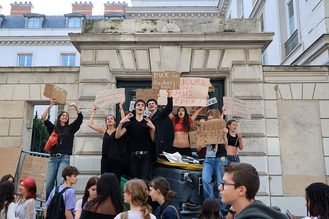
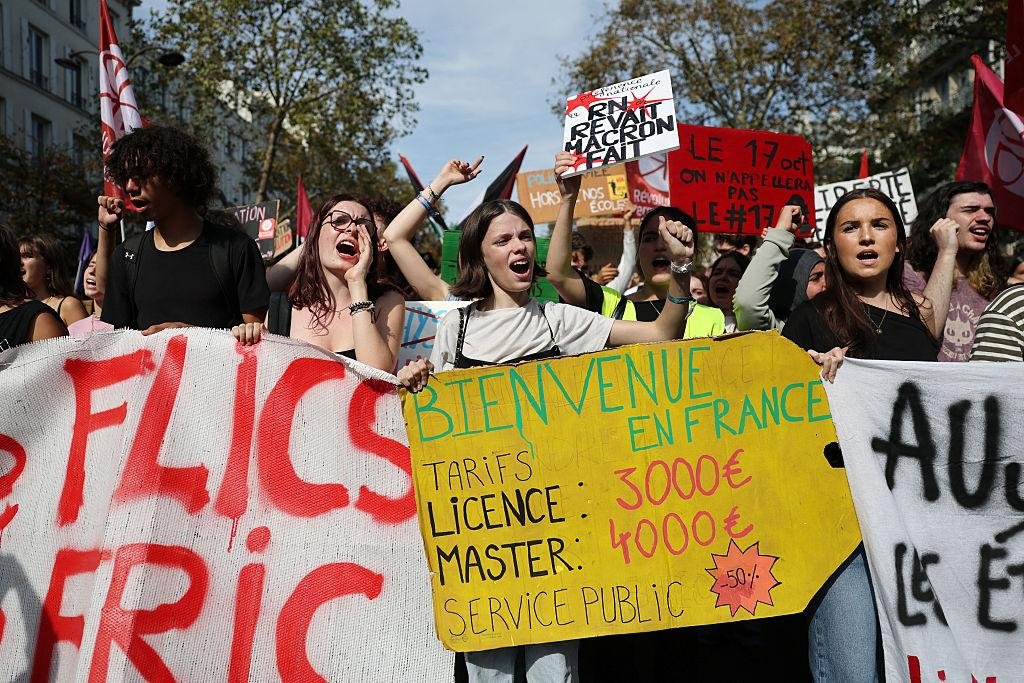
The demonstrations began with complaints about overcrowded classrooms, teacher shortages and deteriorating school buildings. But the protests have quickly grown into a much larger expression of frustration over public services, government spending and the direction of the country.
On October 6, more than 266,000 people took part in demonstrations across France, according to French authorities cited by The Associated Press. About 56,000 protesters were in Paris. Nearly 500 people were detained that day, while more than 6,500 arrests have been reported since the movement began.
The protests are occurring at a difficult economic moment.
France has more than $4 trillion in public debt, while the cost of servicing that debt has increased as government borrowing costs have climbed.
That creates a difficult question for the government: How can France spend more on schools and public services while simultaneously convincing financial markets that its debt is under control?
Why French Students Are Taking to the Streets
France Debt Crisis
The current movement began in the Paris region in September before spreading nationwide.
Students have complained about teacher shortages, overcrowded classrooms, deteriorating facilities and difficult learning conditions. Some have also called for changes to France’s university admissions system.
By October 1, more than 1,020 high schools had been affected by strikes or protests, according to France’s Education Ministry. That represented roughly one-quarter of the country’s high schools at the time.
The movement has since intensified.
Some demonstrations have involved burning garbage, damage to buildings and confrontations with police. The government has condemned violence while acknowledging that students have legitimate concerns about education.
On October 7, France suspended the use of stun grenades by police at student demonstrations following the serious injury of a 15-year-old during a clash. Authorities said the suspension would remain in place while police conduct cases were reviewed.
The protests therefore combine an education crisis with a broader political and economic debate.
The Bigger Problem Is France’s Public Debt
France’s public finances have been under pressure for years.
Official figures show that negotiable French government debt stood at nearly €2.9 trillion at the end of September 2026. The country’s 10-year government bond rate was about 4.83% on October 7, according to France’s debt-management agency.
The broader public-debt figure is even larger.
Public debt reached about €3.595 trillion at the end of June, according to recent French reporting. That was the country’s highest debt level since the aftermath of World War II.
High debt becomes particularly difficult when interest rates rise.
The government must refinance existing debt while also borrowing money to cover current budget deficits. If new borrowing becomes more expensive, more government revenue goes toward interest payments.
That leaves less room for other priorities.
And that is exactly where the student protests become economically important.
Students Want More Investment as the Government Seeks Savings
The French government is facing pressure from two opposite directions.
Students and teachers want more money for education.
Investors want evidence that France can reduce its deficit and stabilize its debt.
Those goals do not necessarily have to conflict forever, but they create a difficult short-term political problem.
Improving school buildings, hiring teachers and reducing classroom overcrowding requires spending.
At the same time, France’s government is trying to implement measures to reduce its deficit.
The proposed 2027 budget includes significant savings efforts, while lawmakers are expected to begin examining the budget in October.
The challenge is particularly sensitive because France is approaching its 2027 presidential election.
Political leaders have limited room to make unpopular spending cuts, but financial markets are increasingly focused on whether France can restore fiscal credibility.
French Bond Yields Are Sending a Warning
One of the clearest signs of financial pressure is the bond market.
France’s 10-year borrowing costs recently approached 5%, reaching levels not seen since 2002. The gap between French and German 10-year borrowing costs has also widened significantly.
Germany’s government bonds are commonly used as a benchmark for euro-area borrowing costs.
When investors demand a larger premium to hold French debt compared with German debt, it can indicate increasing concern about France’s political and fiscal outlook.
This does not mean France is about to default.
It does mean that borrowing is becoming more expensive.
And if higher borrowing costs persist, the government may face an even harder task balancing spending, taxation and deficit reduction.
Why France Matters to the Rest of Europe
France is not a small economy that can experience financial stress without affecting its neighbors.
It is the second-largest economy in the eurozone and one of the world’s major economies.
That makes investors particularly sensitive to developments in French government bonds.
Reuters reported that concerns about possible contagion from rising French yields have already affected confidence in the euro. The euro recently fell below $1.12, while the spread between French and German bonds reached its widest level since the eurozone debt crisis period of 2010-2012.
The concern is not that France’s problems will automatically become another eurozone crisis.
Rather, financial markets are interconnected.
If investors become worried about one major government, they may reassess other countries with high debt or political uncertainty.
That can increase borrowing costs elsewhere.
Could the Crisis Spread Beyond France?
The possibility of financial contagion is one reason economists are watching the situation closely.
If French bond yields continue rising sharply, investors could become more cautious about other heavily indebted European governments.
That could push their borrowing costs higher as well.
The euro could also come under additional pressure if markets believe the European Central Bank may have limited room to respond.
Reuters has reported that concerns about French fiscal instability are already contributing to weakness in the euro and increased market uncertainty.
However, a broader crisis is not inevitable.
Europe has stronger financial institutions and crisis-management tools than it had during the sovereign debt crisis of the early 2010s.
The European Central Bank also has mechanisms designed to address disorderly market conditions.
The key question is whether France can stabilize its finances before market pressure becomes significantly worse.
The Student Protests Add a Political Risk
The economic problem is difficult enough.
The protests make it harder because they increase political pressure on the government.
Prime Minister Sébastien Lecornu’s government is trying to navigate demands for better schools while also managing a difficult budget.
On October 6, more than a quarter-million people participated in nationwide demonstrations, showing how quickly the student movement has grown beyond individual schools.
The protests have also spread into a wider debate about inequality, public services and the country’s future.
That makes a simple budget solution much harder.
A government that cuts spending too aggressively could face more protests.
A government that increases spending without a credible financing plan could face stronger pressure from financial markets.
France is therefore caught between social demands and fiscal constraints.
An Aging Population Adds More Pressure
France’s debt problem is not only about today’s protests.
The country also faces long-term spending pressures.
An aging population means rising pension and healthcare costs.
At the same time, France is increasing defense spending as European governments reassess security priorities.
These demands compete for the same limited public resources.
That means even if the student protests disappear, the underlying budget problem will remain.
The next French government will have to address it.
The 2027 Budget Will Be a Major Test
The 2027 budget could become one of the most important economic tests for France.
Investors will be watching whether lawmakers can agree on a credible plan to reduce the deficit.
Students and public-sector workers will be watching whether spending cuts affect schools and other public services.
Businesses will be watching taxes and economic policy.
European officials will be watching French borrowing costs.
That combination means the budget debate could have consequences far beyond Paris.
A credible fiscal plan could help restore confidence.
A prolonged political deadlock could have the opposite effect.
France Still Has a Path Toward Recovery
The situation is serious, but France is not without options.
The government can attempt to improve spending efficiency, prioritize long-term investment and pursue policies that encourage economic growth.
Education could also become part of the solution rather than simply another budget expense.
Better schools, stronger skills and improved productivity can help expand the economy over time.
That would make the debt burden easier to manage.
The challenge is finding enough money for those investments while keeping government finances credible.
That balance will not be easy.
But it is likely to be central to France’s economic debate over the next several years.
Why Europe Is Watching
France’s student protests began as a fight over school conditions.
They have now become part of a much larger story.
The protests are exposing frustration with public services at the same time that financial markets are questioning France’s fiscal position.
The combination is important because France cannot simply spend its way out of every problem.
Nor can it rely only on spending cuts without considering the social consequences.
Europe is watching because France’s economy is too large to ignore.
If France stabilizes its finances and restores investor confidence, the current turbulence could eventually fade.
If political uncertainty and rising borrowing costs reinforce each other, pressure could spread across European markets.
For now, the second scenario remains a risk, not a certainty.
Important News Takeaway
The France Debt Crisis is unfolding alongside one of the country’s largest recent student protest movements.
Students are demanding better schools, more teachers and improved facilities, while the government is under pressure to reduce a large budget deficit.
At the same time, French borrowing costs have climbed sharply. The country’s 10-year government bond rate was around 4.83% on October 7, according to France’s debt-management agency.
The growing gap between French and German borrowing costs has raised concerns about financial contagion and contributed to pressure on the euro.
Still, France is not facing a confirmed European-wide debt crisis.
The coming months will be crucial. The government’s ability to manage the 2027 budget, calm social unrest and convince investors that French debt remains sustainable could determine whether today’s financial pressure becomes a temporary shock or a much larger European challenge.
THANKS FOR READING