
France Debt Crisis Is Colliding With Growing Student Anger
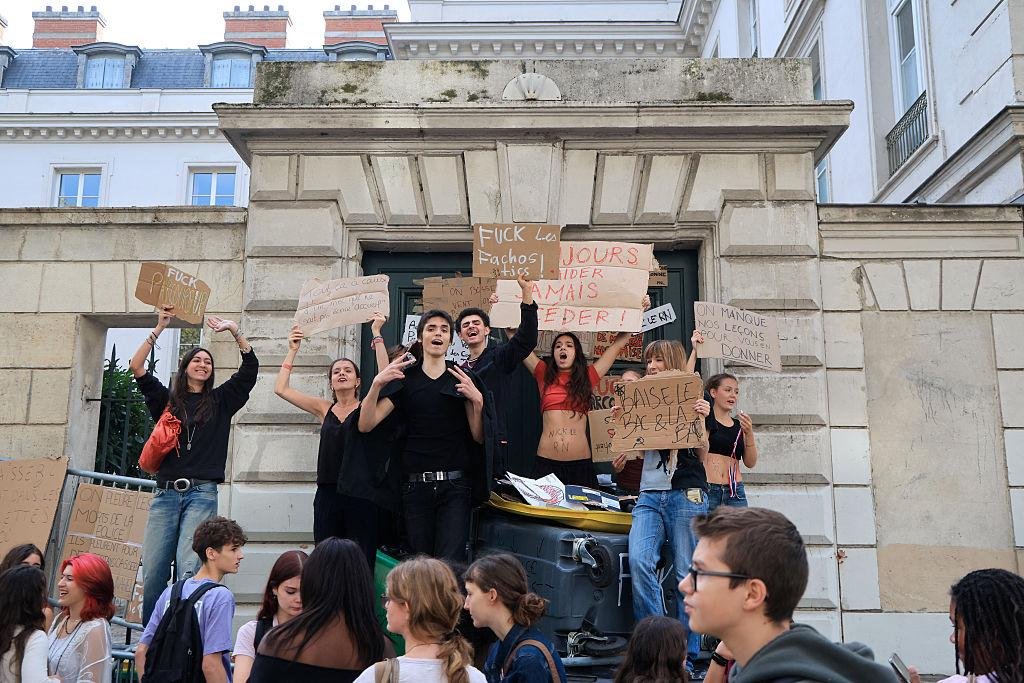
France Debt Crisis concerns are becoming harder to separate from the growing wave of student protests spreading across the country.
What began in September as demonstrations over overcrowded classrooms, teacher shortages and poor school conditions has expanded into a national movement. At the same time, France is facing rising borrowing costs, a huge public debt burden and difficult choices over the government’s 2027 budget.
The combination creates an uncomfortable problem for the French government.
Students are demanding more resources for education at precisely the moment when policymakers are under pressure to control spending.
That tension has turned a dispute about schools into a much broader debate about France’s economic future.
And because France is one of Europe’s largest economies, financial stress there can matter far beyond its borders.
Why Are French Students Protesting?
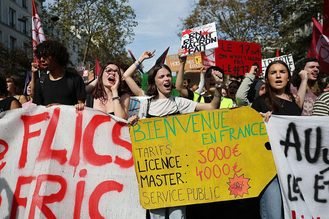
The current student movement began in the Paris region before spreading to other parts of France.
Students have complained about overcrowded classrooms, shortages of teachers, outdated or poorly maintained school buildings, long school days and difficult learning conditions. Some protests have also included broader political and social demands.
By early October, the demonstrations had reached hundreds of schools.
France’s Education Ministry said more than 1,000 high schools were affected by protests or strikes on October 1, including more than 200 blockades.
The movement has not been entirely peaceful. Some demonstrations have resulted in clashes with police, arrests and injuries.
The protests have also attracted support from teachers, unions and other groups, increasing the pressure on the government.
For Prime Minister Sébastien Lecornu’s government, the challenge is especially difficult because responding to the students’ demands could require additional public spending.
The Financial Problem Behind the Protests
France’s public finances were already under pressure before the student demonstrations began.
Public debt reached approximately €3.595 trillion at the end of June 2026, according to recent reporting, its highest level since the end of World War II.
CNN also reported that French public debt exceeded $4 trillion in June and was larger than the country’s annual economic output. The cost of servicing that debt has increased as government bond yields have risen.
That creates a difficult cycle.
When investors demand higher interest rates to lend money to a government, the government must spend more of its budget on interest payments.
That leaves less money available for schools, healthcare, infrastructure and other public services.
France is also dealing with increasing pension costs as its population ages, while defense spending is rising.
The government therefore faces competing demands from several directions.
French Borrowing Costs Are Raising Alarm
One of the clearest warning signs has appeared in France’s bond market.
The country’s 10-year borrowing costs recently reached around 5%, the highest level since 2002, according to Euronews. The gap between French and German borrowing costs has also widened sharply.
Germany is widely treated by investors as a benchmark for relatively safer euro-area government debt.
When investors demand a significantly higher return for French bonds than German bonds, it can signal increased concern about France’s fiscal and political outlook.
That does not automatically mean France is facing an imminent default.
But it does make borrowing more expensive.
And higher borrowing costs can make it even harder for a government to reduce its deficit without making unpopular spending decisions.
Why the Student Protests Matter Economically
At first glance, student demonstrations may appear unrelated to government bond markets.
But there is a direct connection.
Students are asking for more teachers, better facilities and improved education conditions.
Those improvements cost money.
At the same time, investors are demanding evidence that France can bring its deficit and debt under control.
The government therefore has to balance two competing expectations: citizens want better public services, while financial markets want stronger fiscal discipline.
That is one reason the protests have become part of the country’s larger economic debate.
The situation is particularly sensitive ahead of France’s 2027 presidential election.
Could France’s Problems Spread Across Europe?
The biggest concern for European markets is not simply France’s debt level.
It is France’s size.
France is the eurozone’s second-largest economy, meaning financial instability there can have consequences for banks, investors and other countries that are economically connected to it.
Recent bond-market volatility has already raised concerns about spillover effects.
Angel Talavera, chief European economist at Oxford Economics, told CNN that because of France’s size and systemic importance, the potential for contagion into other European countries and the wider eurozone could be significant.
That does not mean a new European debt crisis is guaranteed.
There are important differences between today’s environment and the eurozone crisis of the early 2010s.
European institutions have more experience dealing with sovereign debt stress, and the European Central Bank has tools that were not available in the same form during the earlier crisis.
Still, investors watch France closely because problems in a major economy can affect confidence elsewhere.
Other European Countries Are Watching Closely
France is not the only European country dealing with pressure on public finances.
Several European governments are facing questions about debt, deficits, inflation, energy costs and political divisions.
Higher borrowing costs in one country can influence investor expectations in another.
If investors begin demanding higher yields from multiple governments, financing conditions could become more difficult across the region.
That is why the France Debt Crisis is being watched outside France.
However, it would be misleading to say that France’s problems automatically mean the entire European economy is heading toward a new debt crisis.
The situation remains fluid, and government policies, economic growth, interest rates and investor confidence will all influence what happens next.
The 2027 Budget Is a Major Test
France’s upcoming 2027 budget will be one of the most important tests for the government.
The Treasury plans to issue around €340 billion in debt in 2027, according to Euronews, as the government manages refinancing needs and continued budget pressures.
At the same time, policymakers must decide how much money can be allocated to public services.
Education is one of the areas under pressure.
Students argue that years of underinvestment have contributed to poor facilities and staffing shortages.
The government must therefore find a way to address those concerns without worsening an already difficult fiscal situation.
That is a challenge that cannot be solved simply by increasing spending.
Politics Makes the Situation Even More Difficult
Economic decisions rarely happen in isolation.
France is heading toward a major political transition, with the 2027 presidential election approaching.
That makes spending cuts particularly sensitive.
Reducing public services can trigger protests. Increasing spending can make it harder to convince investors that debt is under control.
Political parties are already using the economic situation to promote competing solutions.
Some favor stronger spending restraint, while others argue that investment in public services is necessary to improve France’s long-term economic prospects.
The student protests have therefore become part of a larger argument over what kind of economic policies France should pursue.
There Is Still a Path Toward Recovery
Despite the serious concerns, France is not without options.
A credible fiscal plan could help restore investor confidence.
Better-targeted public spending could allow the government to protect important services while reducing waste.
Economic growth could also make the debt burden easier to manage over time.
And reforms that improve productivity, education and employment could strengthen France’s ability to generate future tax revenue.
That is why the current debate is not simply about cutting spending.
The bigger question is where France should spend limited public money to produce the strongest long-term results.
Education, infrastructure and economic investment can all contribute to future growth if they are designed effectively.
What the France Debt Crisis Means for Europe
The French student protests have revealed something larger than dissatisfaction with schools.
They have exposed the difficult choices facing a heavily indebted government.
Citizens want better public services.
Investors want fiscal stability.
Politicians must respond to both.
France’s ability to manage those competing demands will be important not only for its own economy but also for confidence across European financial markets.
The most serious risk would come if political uncertainty, rising borrowing costs and weak fiscal credibility reinforced one another.
For now, that remains a risk rather than a certainty.
Important News Takeaway
The France Debt Crisis is developing at a time when students are demanding more investment in education and better public services.
France’s debt has reached historically high levels, while 10-year borrowing costs have risen to levels not seen in more than two decades.
The country’s size means investors are watching closely for signs that financial pressure could spread to other European debt markets.
But a wider European crisis is not inevitable.
France still has opportunities to improve its finances through credible budget policies, economic growth and carefully targeted investment.
The coming months — especially the debate over the 2027 budget — will show whether France can find that balance.
THANKS FOR READING